 Recent analyses indicate that South Africa has managed to achieve a lower debt-to-gross domestic product (GDP) ratio compared to the United Kingdom, recognized as one of the most advanced economies globally.
The debt-to-GDP ratio serves as an essential economic benchmark, illustrating the proportion of government debt relative to the country’s total economic output.
This statistic is a vital point of reference for investors assessing a nation’s economic stability and capability to manage debt obligations.
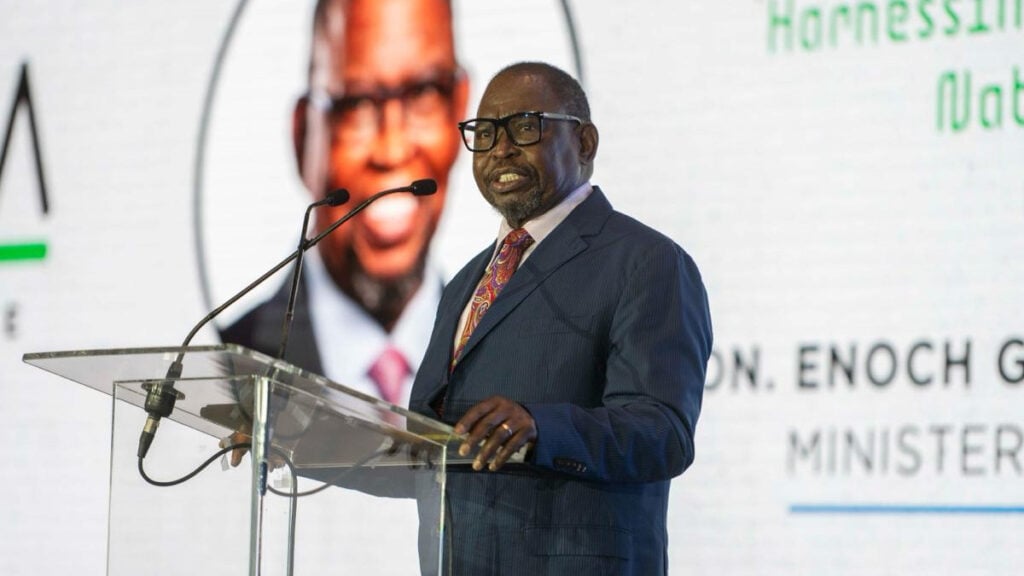
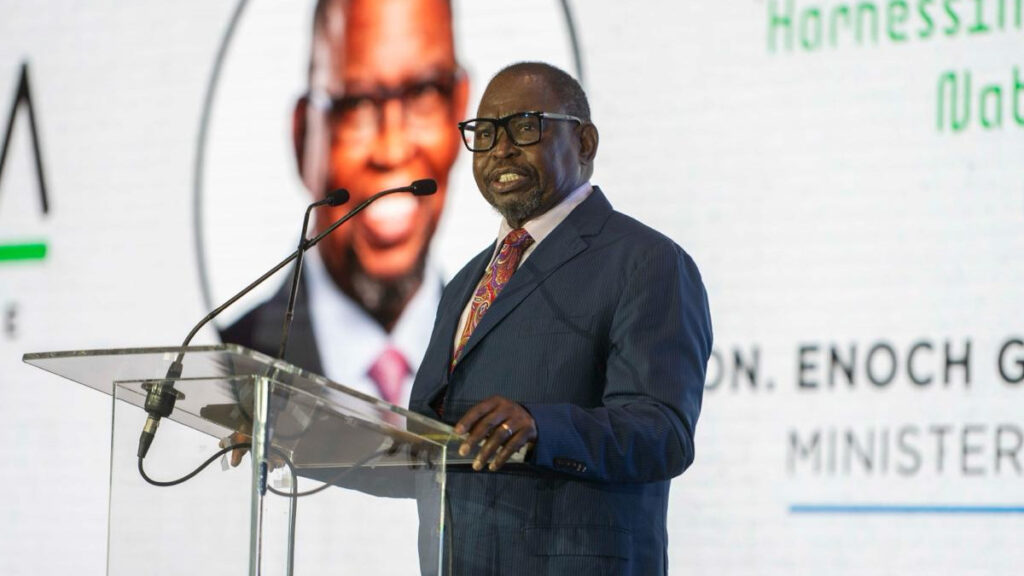
In the latest Medium-Term Budget Policy Statement (MTBPS), Finance Minister Enoch Godongwana reported that South Africa’s debt-to-GDP ratio has stabilized at an estimated 78.4% for 2026.
Looking ahead, the government expects this figure to slide down to 76.6% by the 2029/2030 fiscal year.
Following the recent mini-budget, South Africa’s debt-to-GDP ratio was adjusted downward, influenced by changes in past GDP calculations.
According to the National Treasury, the revisions by Stats SA suggest that the peak government debt could be closer to 74.6%.
“The debt-to-GDP ratio peaked at 74.6% in 2025-26, down from the 78.4% estimated in the 2026 Medium Term Budget Policy Statement,” stated the Treasury.
This adjustment arose from an upward revision of South Africa’s economy, which is now valued at approximately R8 trillion, up from a previous estimate of R7.6 trillion.
The updated GDP figures have led to enhancements in various economic indicators, signaling robust fiscal performance for the nation, as noted by Treasury Director-General Duncan Pieterse.
“Our updated calculations confirm that government continues to meet its fiscal goals, with financial metrics performing better than we expected,” he remarked.
In contrast, the UK’s debt-to-GDP ratio stood at 93.2% by the conclusion of the 2026 financial year, with predictions indicating it could increase to 97.3% by the end of the 2028/2029 period, as reported by the country’s Office for Budget Responsibility (OBR).
“The OBR anticipates that government debt will rise to 97.3% by the end of 2028/29, subsequently declining to about 95.6% of GDP by the close of 2031/32,” the agency conveyed in a research briefing dated 29 October 2026.
UK still on top

Despite the UK’s higher debt-to-GDP ratio, yields on UK government bonds remain significantly lower than those on South African government bonds.
As of 10 November 2026, the yield for South Africa’s benchmark 2035 government bond was recorded at 8.365%, according to Reuters.
Conversely, the British financial firm Hargreaves Lansdown reported a yield of 5.2% on UK 2035 government bonds as of 11 November.
A higher yield on government bonds typically suggests lower confidence in a nation’s ability to honor its debt payments, which is influenced by the debt-to-GDP ratio.
Nonetheless, this ratio is not the sole factor affecting bond yields; a country’s credit rating also plays a critical role.
At present, the UK holds an investment-grade classification from all three leading ratings agencies: Moody’s, Standard & Poor’s (S&P), and Fitch.
In contrast, South Africa is assigned a “junk status” by these agencies, although the nation’s economic outlook appears positive.
This classification indicates a higher risk attached to South African bonds, compelling investors to seek higher returns.
In 2020, following a downgrade by Moody’s, Investec published insights into the circumstances leading to South Africa’s current credit status.
It attributed the downgrades mainly to factors such as “slow economic growth, weak GDP, political instability, challenges in the mining sector, and the burden facing Eskom.”
Currently, various economists predict that South Africa is on the trajectory to reclaim its investment-grade rating, particularly due to its management of government debt levels.
The UK has sustained its favorable credit ratings, notwithstanding its higher debt-to-GDP ratio, due to several influences, including robust financial institutions and a history of fiscal responsibility, according to Jari Stehn, chief European economist at Goldman Sachs Research.
“The UK is equipped with strong fiscal institutions—particularly the OBR, which is highly regarded compared to similar institutions in other nations,” he stated in October 2025.
“Its independence and crucial role contribute significantly, with evidence suggesting that such fiscal institutions enhance better fiscal outcomes.”